The African Development Bank (AfDB) has approved a $150 million financing facility to Equity Bank Kenya Limited to expand access to affordable, long-term credit for small and medium-sized enterprises (SMEs), addressing one of the biggest barriers to business growth across Africa.
The eight-year subordinated loan, approved on October 30, will strengthen Equity Bank’s capital base and increase its capacity to extend financing to businesses seeking to expand operations, acquire equipment, improve productivity and create employment.
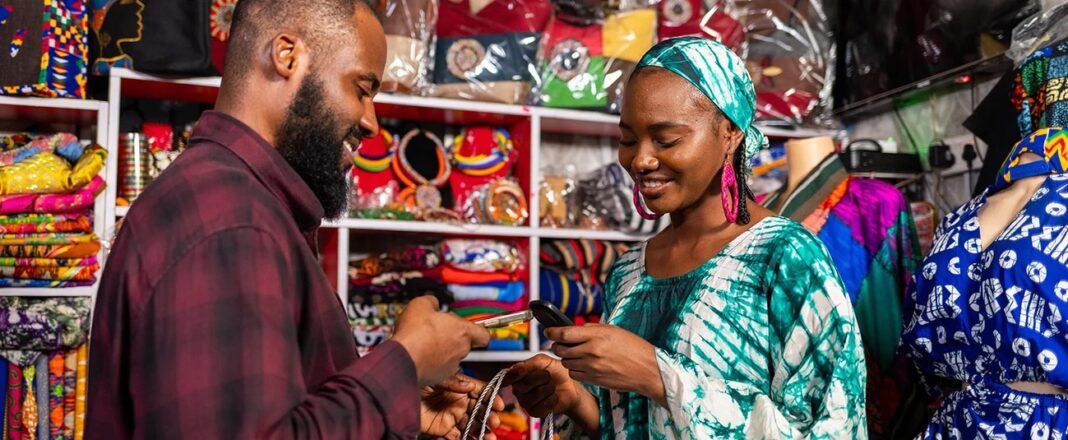
The investment is expected to benefit entrepreneurs across Kenya, particularly those operating in agriculture, manufacturing, trade, logistics and green businesses, with priority attention to women-led enterprises and youth-owned businesses.
The financing comes amid persistent challenges facing African SMEs, many of which struggle to secure affordable credit due to high borrowing costs, limited collateral, short repayment periods and inadequate financial records. These constraints often prevent otherwise viable businesses from investing in expansion, adopting new technologies and accessing larger domestic and international markets.
“Small businesses are the backbone of Kenya’s economy, yet too many entrepreneurs lack the financing needed to turn their ambitions into thriving enterprises,” said Ahmed Attout, Director of Financial Sector Development at the African Development Bank.
“This investment will help unlock opportunities for businesses to grow, create jobs and improve livelihoods. Our priority is to ensure that women and young entrepreneurs have a fair chance to participate in Kenya’s economic growth.”
SMEs contribute more than 30 per cent of Kenya’s gross domestic product and employ over 80 per cent of its workforce, highlighting their importance in driving economic activity, household incomes and employment.
However, access to finance remains a major constraint, particularly for businesses requiring longer-term loans to invest in machinery, technology, production facilities and distribution networks.
Equity Bank Kenya currently serves approximately 1.9 million SME clients nationwide. The new facility will leverage this extensive network to reach businesses in both urban and rural communities.
By 2030, the operation is expected to support approximately 9,000 new SME loans while increasing the proportion of lending directed towards women-led and youth-led enterprises. Equity Bank also aims to increase the intra-African component of its trade finance portfolio, supporting businesses seeking opportunities beyond national borders.
Beyond lending: Building stronger African businesses
The AfDB investment also recognises that expanding SME financing requires more than increasing the amount of money available to banks. Businesses need financial management skills, market information, digital tools and technical support to qualify for credit and use it productively.
To address these challenges, the facility will be complemented by up to $250,000 in technical assistance through the Bank’s Affirmative Finance Action for Women in Africa (AFAWA) initiative.
An additional $900,000 in non-financial support is envisaged through the Bank’s SME Credit Catalyst Programme.
The interventions will strengthen business advisory services, promote digital financing solutions and develop financial products tailored to women and young entrepreneurs.
They will also help SMEs improve financial record-keeping, strengthen business management, access new markets and build resilience against economic and climate-related shocks.
“By combining long-term financing with practical business support, we are helping entrepreneurs overcome barriers to growth, with benefits extending beyond individual businesses to families, communities and the wider economy,” Attout said.
Affordable finance key to Africa’s SME growth
The investment highlights the importance of strengthening financial institutions as channels for directing capital towards productive sectors of African economies.
For SMEs to become stronger contributors to industrialisation, regional trade and employment, financial institutions must expand access to credit products that match the realities of small businesses.
This includes longer repayment periods, competitive interest rates, flexible collateral requirements, working capital facilities and financing linked to business cash flows.
Digital lending platforms and alternative credit assessment systems could also help banks reach informal and emerging enterprises that lack conventional financial records but demonstrate viable business activity.
Expanding financing for women and young entrepreneurs is particularly important given the role of these groups in Africa’s growing business ecosystem.
The facility is expected to support job creation, increase household incomes and improve productivity while encouraging investment in sustainable agriculture, renewable energy and climate-resilient enterprises.
The financing also supports Equity Bank Kenya’s wider $500 million capital-raising initiative, strengthening its ability to lend to businesses that often struggle to obtain affordable, long-term credit. The facility has an eight-year maturity, including a five-year grace period.
“Access to finance can be the difference in whether a business survives or thrives. Investing in small businesses is investing in Kenya’s future,” Attout said.
The operation aligns with the AfDB’s Ten-Year Strategy 2024–2033 and its Cardinal Point 3, which seeks to harness Africa’s demographic dividend for economic development. It also supports the Kenya Country Strategy Paper 2024–2028, which prioritises private sector development, financial inclusion and sustainable economic growth.