For Angela, the financial demands of raising two children who require speech therapy do not end when a treatment session is over. They return with every appointment, every payment and every additional intervention needed to support her children’s development.
At Kenyatta National Hospital, she pays KSh1,550 per child for every speech therapy session. With two children requiring the service, the expense becomes a recurring financial commitment that a household must accommodate alongside food, housing, education and other basic needs.
For her, the cost of disability is not an occasional medical bill. It is a continuing responsibility.
And it is precisely this reality that has brought Kenya’s proposed disability tax exemption regulations under scrutiny, with legislators and disability advocates questioning whether the government fully understands the financial pressures facing people with disabilities and the families who support them.
At the centre of the debate is the Draft Income Tax (Persons with Disabilities, Parents or Guardians Tax Exemptions) Regulations, 2026, which has generated concern over how people will qualify for tax relief, the amount available to caregivers and the administrative requirements applicants must satisfy.
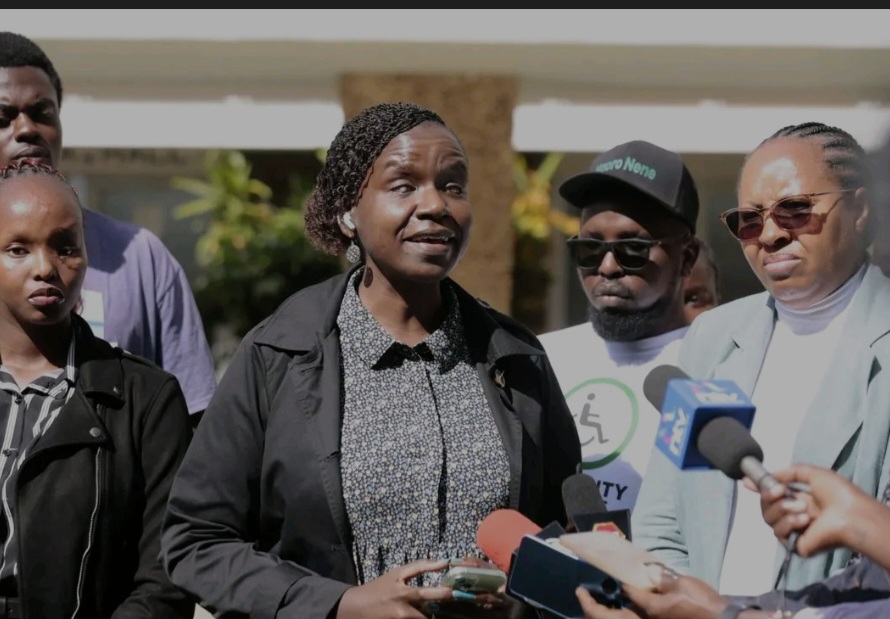
Nominated Senator Crystal Asige argues that the proposals risk creating a system that recognises disability through medical classifications while overlooking the actual costs associated with living with different disabilities.
Her concern is that the financial demands of disability do not necessarily correspond with the severity categories used in medical assessments.
A condition classified as mild does not automatically mean that a family has mild financial responsibilities.
Angela’s experience illustrates this contradiction. The KSh1,550 charged for each child’s speech therapy session remains payable regardless of how the government categorises their condition.
The treatment costs do not become cheaper because a medical assessment assigns a particular severity level.
For families already managing multiple responsibilities, this distinction could determine whether disability-related expenses receive meaningful tax relief or remain an entirely private financial burden.
The same challenge emerges in the experience of Alex, whose hearing impairment requires specialised tests and hearing aids to support his independence.
The cost of hearing assistance extends well beyond purchasing the equipment. There are expenses for moulding, repairs, replacement parts, batteries and specialist consultations to ensure the devices continue functioning effectively.
According to Asige, Alex spends hundreds of thousands of shillings annually maintaining the equipment and accessing specialised services.
These are not necessarily one-time purchases that disappear after the initial investment. Hearing aids require maintenance, adjustments and replacement components, while specialised assessments add another layer of expenditure.
The proposed regulations have therefore raised concerns about people whose hearing loss is not classified as profound or total potentially losing access to full tax relief.
For Asige, such distinctions fail to account for the realities of people who depend on assistive technology to participate in education, employment and everyday life.
The underlying question is whether tax policy should focus exclusively on the medical classification of disability or recognise the continuing financial commitments that individuals and their families must meet.
The debate is particularly significant for caregivers, whose responsibilities often extend beyond financial support to daily assistance, medical appointments, rehabilitation and other forms of care.
Kipipiri Member of Parliament Wanjiku Muhia, speaking in solidarity with persons with disabilities and their families, argues that caregiving households should not be penalised through regulations that fail to recognise the demands placed on them.
She maintains that families caring for people with disabilities experience financial pressures across different levels of disability, including situations where individuals require assistance throughout the day.
In her view, disability should not be graded like a commercial product, with some individuals considered more deserving of support than others.
The proposed KSh10,000 relief cap for parents and guardians has consequently become another point of contention.
Asige wants the amount increased to KSh500,000, arguing that the proposed figure does not adequately reflect the financial demands of supporting a person with a disability.
Muhia also considers the proposed amount insufficient. She said the Kenya Disability Parliamentary Association supports KSh100,000, while other proposals include KSh30,000 and KSh40,000.
The disagreement reflects a broader challenge in designing disability-related tax relief: determining whether the support offered by government corresponds with what families actually spend.
But the financial debate does not end with caregiver allowances.
Asige is also pushing for an increase in the personal income tax exemption threshold for persons with disabilities from the existing KSh150,000 monthly figure to KSh500,000, equivalent to KSh6 million annually.
She argues that the threshold has remained unchanged since 2010, despite inflation and the increasing cost of disability-related services and assistive equipment.
Her proposal is based on the argument that an exemption whose value remains frozen for years gradually loses its ability to provide meaningful financial protection.
She further proposes linking future adjustments to the Kenya National Bureau of Statistics Consumer Price Index, with a formal review every five years.
The intention is to prevent disability-related tax relief from becoming disconnected from the economic realities it is supposed to address.
Yet, beyond the amounts being proposed, another concern is emerging: the cost of qualifying for the relief itself.
Under the draft regulations, applicants face proposed requirements that include medical documentation, reassessment procedures and additional administrative processes.
Asige objects to the proposed non-refundable KSh1,000 application fee, arguing that the Persons with Disabilities Act, 2025, abolished assessment fees.
She also opposes requiring people with permanent disabilities to undergo reassessment every five years, describing the process as an unnecessary burden for individuals whose conditions are not expected to change.
For Muhia, creating another assessment committee risks duplicating existing systems and subjecting applicants to repeated procedures despite already possessing disability certification.
She argues that KRA should rely on existing certification mechanisms instead of introducing additional layers of verification.
For households outside major urban centres, such requirements could create even greater difficulties.
Accessing specialists, obtaining medical reports and travelling to assessment facilities can involve expenses that are not always reflected in the proposed regulations.
In this sense, the administrative process itself becomes part of the cost of disability.
There are also concerns about the proposed requirement for employed applicants to obtain letters from their employers explaining how their disability affects their work.
Asige warns that this could expose employees to unnecessary workplace scrutiny and stigma.
She is also questioning the restriction of specialist medical reports to public health facilities, arguing that this could subject applicants to long queues and delays.
For people already managing medical appointments and the demands of everyday life, obtaining tax relief should not become another complicated process.
The debate has consequently expanded beyond taxation to the wider question of whether Kenya’s disability inclusion policies are accessible in practice.
Muhia has raised concerns about the public participation process, particularly the proposed 14-day notice period and reliance on email submissions.
She argues that people in areas such as Turkana, Eldoret, Kipipiri and Mombasa may not have reliable internet access or electricity to participate effectively in consultations conducted through digital platforms.
More fundamentally, she questions how people with different disabilities can contribute to regulations when the documents themselves may not be accessible to them.
She has called for the draft regulations to be made available in Braille, Kenyan Sign Language and Easy to Read formats for people with intellectual disabilities.
She is also advocating for physical submissions through county and constituency forums to ensure that participation is not restricted to people with internet access.
The concerns raise an important contradiction: a policy intended to improve the lives of persons with disabilities risks being developed through a process that some of its intended beneficiaries may struggle to access.
For Asige, the way forward requires more than adjustments to individual provisions.
Following engagements with senior KRA officials, including Commissioner George Obell, Commissioner Lilian Nyawanda, Deputy Commissioner Maurice Oray and Deputy Commissioner Laura Onyambu, she says there is an opportunity to address the concerns raised by disability representatives.
She wants the proposed regulations aligned with the Persons with Disabilities Act, 2025, alongside appropriate amendments to the Income Tax Act to ensure that the new framework is legally and administratively workable.
Muhia has similarly welcomed the willingness of KRA leadership to engage but says the discussions must translate into written commitments and changes to the proposed framework.
She is calling for the public participation period to be extended by at least 60 days to allow more people with disabilities, caregivers and organisations to submit their views.
The immediate opportunity for public participation remains the November 24, 2026 deadline, with Asige urging affected households and disability organisations to submit memoranda to stakeholder.engagement@kra.go.ke.
Ultimately, the debate surrounding disability tax relief exposes a challenge that goes beyond the interpretation of tax regulations.
For families such as Angela’s, the expenses associated with disability are continuous. For people such as Alex, assistive technology requires sustained financial investment to preserve independence and participation in everyday life.
These costs do not pause when an exemption certificate expires, when a medical assessment is due or when a government threshold remains unchanged.
Nor do caregiving responsibilities disappear because a household has reached a prescribed financial limit.
Kenya’s proposed tax framework therefore presents an opportunity to reconsider what meaningful disability inclusion should look like in practice.
The measure of an effective tax relief system should not simply be how many certificates it issues or how rigorously it classifies applicants. It should also be whether the support reaches the people who need it without imposing additional financial and administrative barriers.
Because for persons with disabilities and the families supporting them, the cost of disability is already substantial.
Accessing the relief intended to ease that cost should not become another expense.